

Instant Cash Advance Loan App
by Fast Online Loans
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
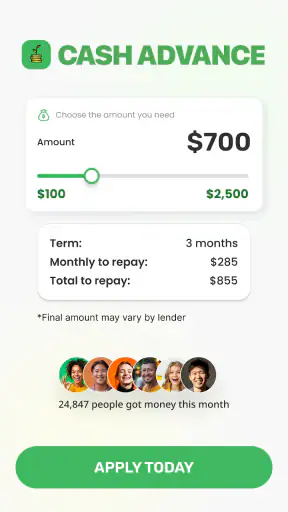
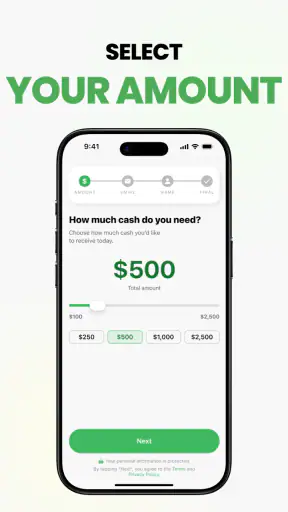
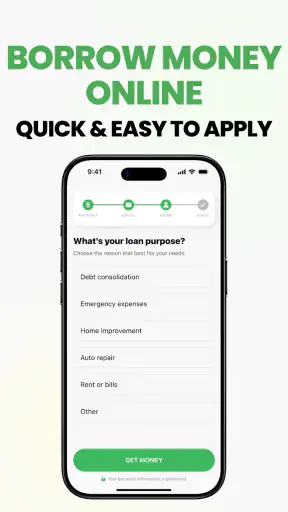
 Analysis by Getfullapps
When money is tight between paydays, the appeal of a cash advance app is obvious: you want a clear route to see whether short-term help is available without spending an afternoon comparing unfamiliar services. Instant Cash Advance Loan App, developed by Fast Online Loans, is built around that narrow need. I found it more useful as a quick borrowing starting point than as a complete personal-finance solution, and that distinction matters before you install it.
This is a free finance app for Android, with an Everyone content rating and support beginning at Android 7.0. Its current version is 2.0.10, and the app has reached more than a million installs. That level of adoption makes it easy to understand why people notice it, but popularity should not be confused with affordability. A loan app can make an application feel simple while the repayment obligation remains serious.
The app holds a 4.6 average from roughly 53 thousand ratings, alongside about 2.3 thousand written reviews. Those figures suggest that many users find the experience approachable, although they do not tell me whether every applicant receives the same outcome. My practical advice is to treat the app as a way to explore a possible cash advance, not as a promise that funds will arrive or that borrowing will be inexpensive.
How the current experience works in real life
I would treat a shared phone as a place to begin an application, not as a shared financial account. Before opening the app, I’d make sure the person considering a loan can use the device privately and review any messages or records themselves. That boundary matters because coordinating household costs is different from letting someone else handle another adult’s borrowing decision.
A focused route for urgent, short-term borrowing
The strongest part of the experience is its focus. Rather than presenting itself as a budgeting suite, investment dashboard, or broad banking replacement, it centers on the idea of applying for a loan quickly. That makes the app relevant when the problem is specific: an unexpected household bill, a gap before a paycheck, or a necessary purchase that cannot reasonably wait.
I would not open it casually when I am merely curious about borrowing. The right moment is when I already know how much I can realistically repay and when I have checked my regular expenses. A fast application can reduce friction, but it can also make an impulsive decision feel harmless. The app is most useful when it supports a plan I have already made rather than creating the plan for me.
A realistic example would be a user whose car needs an urgent repair just before payday. The app may offer a convenient place to begin checking loan availability, but the user still needs to compare the repayment amount with rent, utilities, food, and existing commitments. If repayment would force another loan next month, the convenience has become part of the problem.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What I would check before submitting anything
Before entering personal details, I would first confirm that I am using the genuine listing associated with Fast Online Loans and that my phone meets the Android requirement. I would also read every screen carefully instead of tapping through the application simply because the wording feels familiar. In financial apps, the important information is often in the conditions surrounding repayment, not in the first invitation to apply.
I would keep a written note of the amount requested, the amount expected to be repaid, the due date, and any stated charges. That small habit is one of the most useful ways to avoid confusing the amount received with the total cost. If the final terms differ from what I expected, I would stop and reassess rather than treating the application process as something I must finish.
Another practical tip is to apply only when I can monitor my phone and email afterward. Loan-related decisions may require attention, and missing a message can create avoidable confusion. I would not submit an application while distracted, on a shared device, or through an unsecured public connection. These are simple precautions, but they matter more with financial information than they do with an ordinary entertainment app.
The difference between access and approval
The app’s central promise is speed, but speed should be understood as a quicker application path, not guaranteed approval or guaranteed delivery of money. Those are separate stages. A person can complete an application and still receive terms that do not fit their budget, or no suitable offer at all.
This is where I think new borrowers need the most realistic expectation. A polished mobile flow can make the process feel certain, while lending decisions depend on information and conditions that may vary by applicant. I would therefore avoid making a time-sensitive payment based on the assumption that the app will solve the problem immediately.
If the app presents an offer, I would compare the total repayment rather than focusing only on the requested amount. I would also check whether the repayment schedule fits the date my income actually arrives. A loan that looks manageable using a monthly budget may be difficult if the payment is due before the next reliable paycheck.
Where it differs from usual alternatives
Compared with visiting a traditional bank, a mobile loan app can feel faster and less formal. That convenience may suit someone who needs to begin an application outside branch hours or prefers handling the first steps privately. A bank or credit union may still be the better route for a larger need, a longer repayment period, or a borrower who wants to discuss terms with a person.
Compared with borrowing from friends or family, the app offers a more structured process, but it also places the user into a formal financial obligation. Compared with using a credit card, the right choice depends on the actual cost, the available limit, and how quickly the balance can be cleared. I would never assume that a cash advance is automatically cheaper simply because it is presented in a compact app.
For someone who needs help organizing spending rather than borrowing, this is also the wrong category of tool. A budgeting app, a conversation with a bank, or a payment arrangement with a service provider may solve the underlying issue without adding a new repayment commitment. The narrow focus is a strength only when the user genuinely needs to investigate a loan.
What the current version tells existing users
Version 2.0.10 is the version I would assess today, and its presence gives existing users a concrete reference point when checking whether their installation is current. The app was released on August 15, 2021, so it is not a brand-new product appearing without any history. At the same time, an established release date does not tell me that the borrowing conditions are unchanged over time.
For an existing user, the sensible approach is to update through the normal app store process, then review the screens again instead of assuming that a familiar flow means identical terms. Product changes can affect navigation, wording, eligibility presentation, or how information is requested. Even a small interface adjustment can change where a user notices an important condition.
I would also keep my own records rather than relying on memory from an earlier application. Save the confirmation details that the app provides, note the repayment information, and check the lender-related messages separately. This is especially useful if you return to the app months later, because the fact that the interface looks familiar does not make an old offer current.
Useful habits that make the app safer to use
My first advanced habit would be to calculate a personal borrowing ceiling before opening the application. I would subtract fixed bills, food, transport, and a small emergency margin from my next dependable income. The remaining amount is not automatically safe to borrow, but it gives me a firm boundary and helps prevent the app’s requested amount from becoming my budget.
My second habit would be to compare the loan’s total repayment with at least one alternative before accepting anything. That alternative might be a bank product, a credit-union conversation, a payment extension, or delaying a nonessential purchase. The comparison does not need to be complicated; the important point is to compare the complete obligation, not just how quickly the application can be completed.
My third habit would be to separate the application decision from the emergency itself. When a bill feels urgent, I would first call the company involved and ask whether a due-date change or installment arrangement exists. If that option works, it may be less expensive than borrowing. The app remains useful as one route to investigate, but it should not be the only route considered under pressure.
A fourth useful check is to think about repeat use. If I need a cash advance every pay period, the issue is probably larger than one temporary gap. In that situation, I would pause applications and look at recurring expenses, income timing, debt counseling, or a longer-term banking solution. The app may help with one isolated emergency, but repeated reliance can make a short-term tool behave like a permanent debt cycle.
Where the experience still needs caution
The biggest limitation is not necessarily the app’s interface; it is the distance between a quick application and a financially suitable outcome. A streamlined process can be helpful, yet it cannot decide whether borrowing is wise for my particular budget. That responsibility remains with me, and the app does not replace careful reading of the final terms.
I also would not treat the high average rating as evidence that a loan will work equally well for everyone. Ratings describe user experiences with the product, while approval, amount, repayment conditions, and personal affordability are individual matters. Written reviews can help reveal common frustrations, but they should be read as context rather than as a substitute for examining an offer myself.
Privacy deserves deliberate attention too. Any finance application involves sensitive information, so I would review the permissions and privacy explanations displayed during installation and use. I would avoid sharing information that is not clearly relevant, and I would remove the app from a device I no longer control. These steps are not reasons to reject the app automatically; they are basic safeguards for any mobile borrowing service.
The app is also not the right choice for someone who needs a guaranteed amount by a guaranteed deadline. Its name may create that expectation, but a responsible user should plan as though the application could take longer, produce different terms, or fail to meet the need. If missing a payment would cause serious harm, I would contact the creditor directly and explore alternatives before relying on a prospective loan.
Who should use it, and who should skip it
I can see the value for an adult Android user who has a one-off short-term cash gap, understands the difference between applying and receiving funds, and is willing to compare the full repayment obligation. The free download and focused purpose make it a convenient first step for that person, particularly when visiting a branch is impractical.
I would advise skipping it if the goal is general money management, long-term debt reduction, or guaranteed emergency funding. I would also be cautious if income is irregular, existing repayments already consume most of the budget, or the requested loan would cover another loan. In those cases, a bank adviser, nonprofit debt counselor, creditor arrangement, or carefully reviewed alternative may be more appropriate.
Age labeling also deserves a sensible interpretation. Although the app is marked for Everyone, that does not mean every person should borrow. The label concerns content suitability, not financial readiness, legal eligibility, or the ability to repay. I would judge the product by my circumstances and the terms shown to me, not by the general audience label.
What I would watch as the product evolves
For future updates, I would pay attention to how clearly the app explains repayment totals, due dates, eligibility, and any conditions before an application is finalized. Those details matter more to me than cosmetic changes. A faster screen is useful, but transparent financial information is what makes speed responsible.
I would also watch whether the experience remains consistent for returning users. Existing borrowers need to recognize their application status, repayment information, and support route without searching through a redesigned interface. If a new version changes the flow, clear explanations would be more valuable than simply adding more prompts.
Another sign of progress would be stronger support for informed decisions without turning the app into a different product. Helpful reminders to review affordability, clear distinctions between requested and repayable amounts, and easy access to records would improve the experience. I would welcome those changes because they reduce mistakes without pretending that borrowing is risk-free.
My final view after weighing convenience against cost
Instant Cash Advance Loan App is a focused way to begin exploring short-term borrowing, and its large installed base and strong average rating show that it has attracted considerable attention. I like the direct purpose and the fact that it can be approached from a phone rather than requiring a branch visit. For a carefully prepared applicant, that can be genuinely convenient.
Still, I would not describe it as a financial safety net. The app can simplify the first step, but it cannot make an expensive loan affordable, guarantee approval, or remove the consequences of missed repayment. My recommendation is to use it only after calculating what I can repay, comparing alternatives, and reading the complete offer slowly.
In short, this is worth considering for a specific, isolated cash shortfall, not for routine spending or ongoing debt. If I needed to decide today, I would install it only with a written budget beside me and a backup plan that does not depend on approval. That approach preserves the app’s convenience while keeping the most important decision in my hands.
Pros
- Fast application process with minimal paperwork required
- Clear repayment schedules help users plan upcoming payments
- Available from a smartphone without visiting a physical branch
- Useful for covering unexpected short-term expenses
- Application status updates are easy to follow
Cons
- Interest and service fees may make borrowing expensive
- Approval and loan amounts depend on eligibility checks
- Late payments can lead to extra fees or collection activity
- Not available in every state or for every applicant
- Repeated borrowing may create a difficult debt cycle
FAQs for Instant Cash Advance Loan App
What is the Instant Cash Advance Loan App, and how does it work?
Instant Cash Advance Loan App is designed to let eligible users request short-term cash advances from a mobile device. After creating an account, you typically provide personal, employment, income, and banking information so the service can assess eligibility. If approved, the app displays the advance amount, fees, repayment date, and applicable terms before you accept the offer. Approval and funding are not guaranteed, and processing times may vary.
What information and permissions does the app require?
During registration, the app may request details such as your legal name, address, date of birth, employment information, income, bank account details, and contact information. Depending on the provider, it may also request permissions related to notifications, device data, or account verification. Before continuing, review the privacy policy and permission settings carefully. Only provide accurate information through the official app or website, and avoid sharing banking credentials through unofficial channels.
How much does borrowing through the app cost?
The total cost depends on the lender, the amount borrowed, your repayment schedule, and any applicable service, origination, subscription, expedited-funding, or late fees. Some cash advance services advertise no traditional interest but may still charge optional or mandatory fees. Carefully review the annual percentage rate when provided, the total repayment amount, and every fee before accepting an offer. Never rely only on the advertised advance amount when comparing loan options.
When will I receive the money, and how is repayment handled?
Funding speed depends on approval, identity verification, your bank, and whether you select standard or expedited delivery. Some users may receive funds quickly, while others may experience delays or additional verification requests. Repayment is commonly scheduled automatically from a linked bank account on a stated date, although available options vary. Confirm the repayment date, account balance requirements, extension policy, and consequences of a failed payment before accepting the advance.
Is the Instant Cash Advance Loan App safe and available to everyone?
Safety and availability depend on the specific company operating the app, your location, and its eligibility requirements. Before downloading, verify that the application comes from the correct developer, uses secure connections, and provides clear contact, licensing, privacy, and lending information. These services may not be available in every state or country, and approval can depend on age, income, banking history, and other criteria. A cash advance should be used cautiously because repeated borrowing or missed repayment may create additional financial pressure.

Instant Cash Advance Loan App
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via info@moneyborrowing.app, visit https://moneyborrowing.app, or review their https://moneyborrowing.app/privacy-policy/.










